
WHEN A BANK SUCCEEDS, MUST A PATHOLOGICAL CRITIC INVENT A CRIME? — PART 3
Correcting the Viral Numbers, Defending Abia with Evidence, and Separating Banking Growth from Allegations of Public-Fund Diversion
The latest attack on Signature Bank has now moved beyond suspicion into statistical theatre.
A viral e-flyer has been circulated presenting Signature Bank beside Zenith Bank, GTCO, Access Holdings and major international banks, with the suggestion that the bank’s rapid growth is so extraordinary that something improper must explain it.
That argument deserves scrutiny.
But once the figures are properly checked, an uncomfortable fact emerges:
Some of the numbers used in the viral comparison are simply wrong.
Others mix different periods or definitions.
And none of them proves that Abia State Government money is responsible for Signature Bank’s growth.
That is where the evidence must begin.
PART ONE: WHAT WE ESTABLISHED BEFORE OUR MAIDEN FLO FM MEDIA CHAT
Before our maiden media engagement on FLO FM, the allegation being circulated was that Abia State funds, including money linked in political commentary to public projects, were supposedly being warehoused in Signature Bank.
Our response was simple.
If Abia State money is in Signature Bank, produce the evidence.
Identify the government account.
State the account title.
Identify the ministry, department or agency.
State the amount.
Give the date.
Produce the treasury mandate.
Produce the bank statement.
Produce the transfer instruction.
Show the corresponding credit.
Then show how the transaction breached the law.
That remains the correct evidentiary standard.
A social-media post is not a bank statement.
A rumour is not a payment mandate.
A political allegation is not an audit finding.
PART TWO: ASSOCIATION IS NOT APPROPRIATION
Part Two dealt with the attempt to turn personal and professional association into proof of financial misconduct.
Dr Alex Otti was publicly associated with the establishment of Signature Bank before becoming Governor of Abia State.
Signature Bank commenced operations in November 2022.
Otti assumed office as Governor in May 2023.
Those are public facts.
But the proposition:
Otti was associated with Signature Bank
does not logically establish:
Abia State money was diverted to Signature Bank.
A historical association can justify scrutiny.
It cannot substitute for evidence of an unlawful transfer.
The same principle applies to board relationships, corporate connections and contractor relationships.
Those facts may justify questions.
They do not complete a money trail.
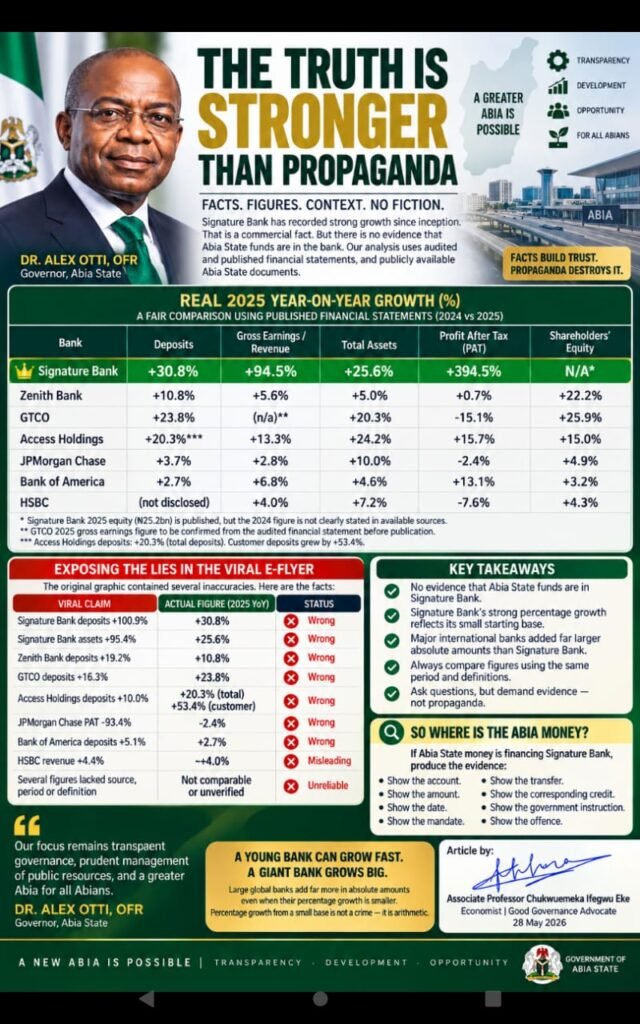
PART THREE: THE VIRAL E-FLYER FAILS ITS OWN FACT-CHECK
The original viral graphic attempted to show that Signature Bank “outperformed all the banks in the world.”
It compared Signature Bank with institutions including Zenith Bank, GTCO, Access Holdings, JPMorgan Chase, Bank of America, HSBC and others.
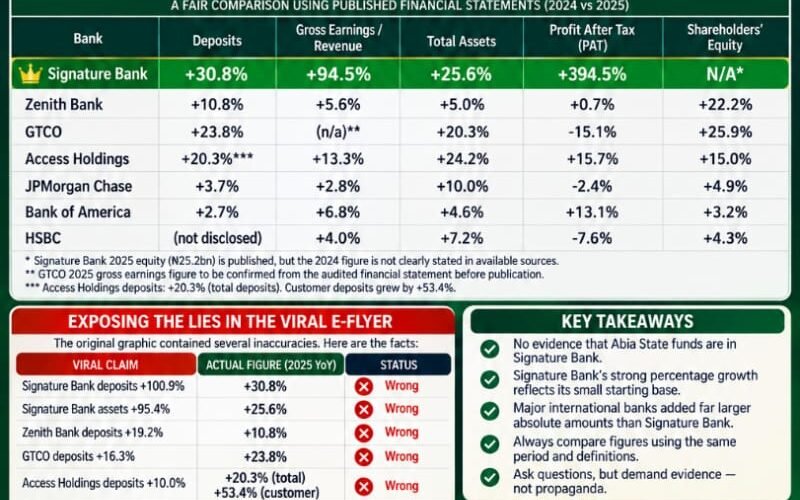
But once the figures are benchmarked properly on a consistent 2024-to-2025 year-on-year basis, several claims in that graphic fall apart.
Consider Signature Bank itself.
Published 2025 results show customer deposits of approximately ₦170.8 billion, against about ₦130.59 billion in 2024.
That is growth of approximately 30.8%.
The viral graphic claimed 100.9%.
That claim does not match the published 2024-to-2025 comparison.
Total assets increased from approximately ₦178.86 billion to ₦224.7 billion.
That is growth of approximately 25.6%.
The viral graphic claimed 95.4%.
Again, that does not match the published 2025 year-on-year figures.
Gross earnings rose by approximately 94.5%.
That figure is supported.
Profit after tax rose from about ₦726 million to ₦3.59 billion.
That produces approximately 394.5% growth.
That figure is also broadly correct.
So the proper Signature Bank comparison is:
Deposits: +30.8%
Gross earnings: +94.5%
Assets: +25.6%
PAT: +394.5%
Not the mixture of figures originally presented.
THE ORIGINAL FLYER ALSO MISSTATED OTHER BANKS
Zenith Bank’s 2025 audited results show:
Deposits: approximately +10.8%
Gross earnings: +5.6%
Total assets: +5.0%
Profit after tax: +0.7%
Shareholders’ funds: +22.2%
Yet the viral flyer gave Zenith deposit growth of 19.2%.
That was wrong.
GTCO’s published 2025 results show:
Deposit liabilities: +23.8%
Total assets: approximately +20.3%
Profit after tax: approximately -15.1%
Shareholders’ funds: approximately +25.9%
The viral flyer gave GTCO deposit growth of 16.3%.
Again, that was wrong.
Access Holdings also demonstrates why definitions matter.
Depending on whether one uses total deposits or customer deposits, the growth rate differs significantly.
The original graphic simply presented a 10.0% figure without adequately identifying the measure being used.
That is not good empirical practice.
If different institutions are measured using different definitions, the comparison becomes misleading.
JPMORGAN CHASE: THE MOST GLARING ERROR
The viral graphic claimed JPMorgan Chase suffered a 93.4% decline in profit after tax.
That figure is not supported by its 2025 results.
Its net income declined only modestly year on year.
That alone should have warned readers that the original e-flyer was not a reliable financial benchmark.
A figure of -93.4% creates the dramatic impression that one of the largest banks in the world had almost lost its entire annual profit.
That is not what happened.
Once one of the most dramatic figures in a comparative table is materially wrong, the entire table deserves re-examination.
THE CORRECT LESSON IS NOT THAT SIGNATURE BANK “BEAT THE WORLD”
The corrected numbers tell a more sober story.
Signature Bank is a young institution.
It is growing from a very small base.
That matters enormously when interpreting percentage growth.
A company that moves from ₦1 billion to ₦4 billion records 300% growth.
A company that moves from ₦5 trillion to ₦6 trillion records only 20%.
Yet the second company added ₦1 trillion.
The first added just ₦3 billion.
Percentage growth measures the rate of change.
It does not measure absolute scale.
It does not measure market dominance.
And it certainly does not establish criminality.
This is the elementary base-effect problem.
SIGNATURE BANK’S GROWTH SHOULD BE ANALYSED, NOT CRIMINALISED
Signature Bank’s rapid growth is legitimate material for commercial and regulatory analysis.
Regulators may properly ask:
How concentrated are its deposits?
Who are its largest customers?
How rapidly is its loan book expanding?
What is its liquidity profile?
What is its capital adequacy position?
What are its related-party exposures?
Those are legitimate banking questions.
But those questions are completely different from the accusation that Abia State Government money is secretly responsible for the bank’s expansion.
The latter requires evidence of actual government transfers.
WHERE IS THE EVIDENCE THAT ABIA STATE IS FUNDING SIGNATURE BANK?
Abia State’s published financial statements provide schedules of government banking relationships.
The 2023 Auditor-General’s financial statements list a range of banks holding or handling state-related accounts.
Among those identified are institutions such as Access Bank, Fidelity Bank, Zenith Bank, GTBank and others.
In the published account schedule reviewed, Signature Bank does not appear.
The 2024 Accountant-General records similarly identify multiple government accounts and balances with established banks.
Again, the published schedules reviewed do not establish Signature Bank as the repository supposedly responsible for its growth.
That is significant.
It does not justify making an absolute claim that no government-related transaction of any conceivable kind could ever involve Signature Bank.
But it does establish this:
The published Abia State financial-account schedules reviewed do not substantiate the allegation that Signature Bank is being financed by Abia State Government money.
That is the documentary position.
The 2023 Auditor-General schedule identifies existing government banking relationships, while the State’s public financial-report portal makes the relevant documents available for scrutiny. 0
THE KPMG RECORD POINTS TO OTHER BANKS
The KPMG forensic material relating to Abia State Government revenue collection identifies specific banks that received documented government collections.
The report identifies Zenith Bank, Access Bank and Fidelity Bank in the relevant collection arrangements.
For example, it records Abia State Consolidated IGR and BIR-related accounts with those institutions.
Signature Bank is not identified in that table as one of the banks receiving the documented collections under review. 1
Again, this is documentary evidence.
Not political sentiment.
If critics possess contrary documentary evidence, they should produce it.
THE PROPER BENCHMARK SHOWS SOMETHING VERY DIFFERENT
The corrected 2025 benchmark gives a clearer picture.
Signature Bank:
Deposits: +30.8%
Gross earnings: +94.5%
Assets: +25.6%
PAT: +394.5%
Zenith Bank:
Deposits: +10.8%
Gross earnings: +5.6%
Assets: +5.0%
PAT: +0.7%
Shareholders’ funds: +22.2%
Zenith’s audited report confirms those 2025 movements. 2
GTCO:
Deposit liabilities: +23.8%
Total assets: approximately +20.3%
PAT: approximately -15.1%
Shareholders’ funds: approximately +25.9%
GTCO’s audited results confirm deposits rising from ₦10.40 trillion to ₦12.87 trillion, while PAT declined from ₦1.02 trillion to ₦865.75 billion. 3
Signature Bank’s own 2025 published figures confirm PAT of ₦3.59 billion, gross earnings of ₦24.99 billion, assets of ₦224.7 billion and deposits of ₦170.8 billion. 4
What do these figures actually show?
They show that Signature Bank recorded very high percentage growth in several categories.
They do not show that Signature Bank is larger than Zenith.
They do not show that it is larger than GTCO.
They do not show that it is larger than JPMorgan Chase.
And they certainly do not show that Abia State Government money caused that growth.
A YOUNG BANK CAN GROW FAST; A GIANT BANK GROWS BIG
This distinction is central.
Signature Bank can post very high percentage growth because it is starting from a comparatively small balance sheet.
Large banks can add vastly more money in absolute terms while recording smaller percentage changes.
That is why comparing a young bank directly with global banking giants purely by percentage growth without controlling for scale is statistically crude.
A sapling can double in height.
An iroko cannot.
That does not make the sapling fraudulent.
THE 394.5% PROFIT FIGURE NEEDS CONTEXT
The 394.5% PAT increase sounds spectacular.
It is spectacular.
But context matters.
Signature Bank’s PAT rose from approximately ₦726 million in 2024 to ₦3.59 billion in 2025. 5
That is a large percentage increase because the starting profit base was small.
This is not an argument against investigating banks.
It is an argument against pretending that percentage growth itself is proof of a financial crime.
A percentage cannot tell us who deposited the money.
A percentage cannot identify a government transfer.
A percentage cannot establish diversion.
A percentage cannot substitute for a bank statement.
CIRCUMSTANTIAL EVIDENCE CANNOT FILL A MISSING FINANCIAL LINK
Consider the allegation being constructed:
Otti was associated with Signature Bank.
Otti became Governor.
Signature Bank grew.
Some individuals had relationships with contractors.
Government awarded contracts.
Therefore Abia State money must be financing Signature Bank.
That chain is incomplete.
Where is the debit from the government account?
Where is the corresponding credit?
Which ministry?
Which agency?
Which contractor?
Which escrow account?
Which treasury mandate?
Which authorising officer?
What amount?
What date?
What unlawful benefit?
Without those links, what exists is a theory.
Not proof.
ASK QUESTIONS — BUT DO NOT INVENT THE ANSWERS
Every serious citizen should support scrutiny.
Ask whether Abia State has any account at Signature Bank.
Ask whether any MDA operates an account there.
Ask whether contractors maintain accounts there.
Ask whether project escrow accounts exist there.
Ask whether related-party transactions have been properly disclosed.
Ask whether regulatory compliance requirements have been satisfied.
Those are proper questions.
But once the claim becomes:
“Abia State money is floating Signature Bank,”
the burden changes.
That is no longer a question.
It is an allegation of fact.
And it requires evidence.
SO WHERE IS THE ABIA STATE MONEY?
If Abia State money is supposedly responsible for Signature Bank’s growth:
Show the account.
Show the amount.
Show the date.
Show the mandate.
Show the transfer.
Show the corresponding credit.
Show the government instruction.
Show the unlawful benefit.
Show the offence.
Until that documentary bridge is produced, rapid growth remains evidence of rapid growth.
It is not evidence of diversion.
The original viral e-flyer exaggerated or misstated several comparative banking figures.
The corrected figures show that Signature Bank’s percentage growth is indeed strong.
But the corrected figures also expose the central fallacy.
High percentage growth from a small base is not a crime.
A commercial relationship is not a payment mandate.
A boardroom association is not a bank transfer.
A political suspicion is not an audit finding.
And a colourful e-flyer cannot replace forensic accounting.
The published Abia State financial records reviewed do not establish that Abia State Government funds are responsible for the growth of Signature Bank.
That is where the evidence presently stands.
AProf Chukwuemeka Ifegwu Eke
Economist | Good Governance Advocate